For many Australians, retirement is no longer simply a question of whether they have accumulated enough money, it’s also about whether they feel confident enough to enjoy the life they have worked towards.
That confidence can be surprisingly difficult to arrive at.

The cost of living, healthcare expenses, volatile investment markets and longer life expectancies all make retirement planning more complex. At the same time, superannuation and retirement policy continues to evolve. Even when changes are intended to improve the system, speculation and media discussion can leave people wondering whether the plans they make today will still work tomorrow.

A recent survey found that only 52 per cent of Australians felt financially confident about retirement.i

Decisions and complexity

Australians are generally making decisions about superannuation, investments, tax, retirement income and government benefits, many years before they retire. However, important questions need to be asked before making a decision as these can have a significant impact at retirement.

Common retirement questions to consider include: When should I retire? How much can I afford to spend? Should I contribute more? Should my investment portfolio change?

Changes to the superannuation system can add another layer of complexity to these questions and so can discussions about possible changes. A media headline about superannuation or tax can prompt people to question whether their existing strategy remains appropriate, even when the proposed change may have little or no impact on them personally.

This is not an argument against reform – Australia’s retirement system needs to evolve to meet the needs of a changing society – but it does highlight the importance of having someone who can put changes into context.

With heightened geopolitical tension and market volatility, rising household budgets and healthcare pressures, these factors further impact how pre-retirees and those who have already retired, are feeling about their financial future.

Knowledge builds confidence

Research reveals that Australians who had a clear understanding of the actions they needed to take were three times more likely to feel highly confident about supporting their desired lifestyle in retirement.ii

It also matters for another reason. Lacking retirement confidence does not always sway people to save more in the years leading up to retirement, but it can lead them to spend less than they comfortably could afford to once they stop work.

Australia’s Retirement Income Review noted that many retirees were drawing down very little of their capital and that most people died with a substantial proportion of their wealth still intact.iii This does not mean leaving an inheritance is a bad outcome, but it does suggest that some people may be more cautious about spending money than they need to be.

For someone who has spent decades accumulating and protecting wealth, transitioning from saving to spending can be psychologically difficult. Without a clear understanding of what is sustainable, it can be tempting to keep working, delay experiences or simply spend less than their financial position allows.

The objective is not to encourage people to spend for the sake of spending. It is to give them the knowledge and confidence to make deliberate choices about their retirement lifestyle.

Confidence is about choice

Ultimately, retirement confidence should not be measured solely by whether someone believes they have “enough”.

It is about knowing what is possible. Can you travel? Help your children or grandchildren? Renovate the house? Pursue an interest? Spend more in the early years of retirement while you are healthy enough to enjoy it?

A good retirement plan should help answer those questions.

For some people, confidence may mean knowing they can afford to spend more than they initially thought. For others, it may mean making different choices about investments, tax or the timing of retirement. The important thing is knowing what choices to make.

Australia’s retirement system will continue to evolve. There will always be another announcement, another review and another headline about superannuation or tax.

The answer is not to try to predict every change. It is to have a plan that can adapt, and the knowledge to understand what those changes mean for you.

Because confidence in retirement is not simply knowing how much you have. It is knowing what you can do with it.

i AMP | Retirement Confidence Pulse 2026
ii
Vanguard | How Australia Retires 2025
iii
Australian Government Treasury | Retirement Income Review Final Report

Find unclaimed money

There is around $3 billion in lost shares, bank accounts and life insurance. You may have money that has not been claimed.

Important: Can’t see an address? Only limited address information is displayed on public unclaimed money records. If you think you have a legitimate claim to a record of money, you will need to provide proof of any addresses in the listed suburb.

Claiming money is a free service

Finding unclaimed money is a free service provided by the Australian Government.

There are services that can help you claim, but they follow the same process as if you claim yourself. They may also charge you a fee.

If you do choose to use a claim service, make sure the person you work with is a registered professional, such as a lawyer, accountant or financial adviser.

Using a registered professional gives you more protections, as it means they:

  • Are registered with a professional association

  • Must meet educational, experience and ethical standards

  • Are subject to codes of conduct and disciplinary action

Why has my money become unclaimed?

The Australian Government has laws to ensure that if money is identified as ‘unclaimed’, it can be returned to the rightful owner.

Under the unclaimed money laws, organisations are required to send unclaimed money to the Australian Securities and Investments Commission (ASIC). ASIC maintains the unclaimed money records and assists in the process to reunite unclaimed money to the rightful owners. Unclaimed money sent to ASIC is transferred to the Commonwealth of Australia Consolidated Revenue Fund.

Money may become unclaimed for the following reasons:

  • Bank accounts – if the account has been inactive (no deposit or withdrawals) for 7 years.

  • Life insurance policy – becomes unclaimed 7 years after the policy matures and is not claimed.

  • A company cannot contact a shareholder for more than 6 years.

  • A member of a managed investment scheme cannot be contacted for more than 6 years.

  • Money has been paid to a financial product provider for a financial product that cannot be issued and the money cannot be returned.

  • The money is the property of a deregistered company, or property of a trust or superannuation fund where a deregistered company is acting as trustee.

  • There is unclaimed money after:

    • a compulsory acquisition of securities

    • the winding up of managed investment scheme

    • the liquidation of a company

Depending on the type of claim, ASIC or the relevant institution will process your claim. Lost money is available to be claimed at any time by the rightful owner and there is no time limit on claims.

Didn’t find any lost money?

If you think you still have lost money, contact the institution where you think you had it. All records received by ASIC are publicly displayed on this list. We do not have access to any other records held by other agencies or institutions.

You can search for other types of unclaimed money on other government websites:

  • Australian Taxation Office – Search for lost superannuation by registering for the Australian Taxation Office’s online services via myGov.

  • State government – Search State government websites for deceased estates, lost share dividends, salaries and wages, cheques, over-payments, proceeds of sale and more.

Interest paid on unclaimed money

Interest is paid on unclaimed money, calculated from 1 July 2013. Find out more about how interest is paid.

What is an Original Transaction Number (OTN)?

Each unclaimed money record is given a unique OTN. You will need this number to make a claim. The OTN will also help you relocate that record in future and will assist us if we need to discuss your claim.

What life insurance money is held by ASIC?

ASIC holds money from life insurance policies from insurance companies or friendly societies that have been unclaimed for 7 years after the policy matures. ASIC’s unclaimed money search database goes back to 1952 for life insurance companies and back to 2000 for friendly societies.

What bank account money is held by ASIC?

ASIC holds money from bank, credit union and building society accounts that have not been used in 7 years and contain a balance of $500 or more.  ASIC’s unclaimed monies online search database holds these bank records:

  • savings bank accounts – records from 1989 

  • trading bank accounts – records from 1959 

  • credit union and building society accounts – records from 1992.

If the account you are looking for was last accessed before 1992, contact the state or territory government’s office of state revenue or state treasury where the bank, credit union or building society was originally registered. For example, if the credit union or building society was registered in NSW, you will need to go to Revenue NSW.

What money under the Corporations Act is held by ASIC, and how can I claim it?

ASIC holds certain types of unclaimed money from companies, shares and investments when the rightful owner cannot be located or the money has not been claimed. This can include money from lost shareholders, deregistered companies, company liquidations, managed investment schemes and other situations covered by the Corporations Act. 

If you find your name on the MoneySmart Unclaimed Money Search and the record is listed as “Company money”, you can lodge a claim directly with ASIC. To claim, note your Original Transaction Number (OTN), complete the relevant claim form, and provide documents that prove your identity and entitlement to the money. ASIC will assess your claim and, if approved, pay the funds directly to you.

Where does the data come from?

The data shown in search results is supplied by various banks, building societies, credit union, life companies, friendly societies and registered Australian companies. ASIC does not make any guarantees regarding the accuracy, currency, or completeness of the data. For privacy reasons some information may be redacted.

Source: Moneysmart
Reproduced with the permission of ASIC’s MoneySmart Team. This article was originally published at https://moneysmart.gov.au/find-unclaimed-money
Important note: This provides general information and hasn’t taken your circumstances into account.  It’s important to consider your particular circumstances before deciding what’s right for you. Although the information is from sources considered reliable, we do not guarantee that it is accurate or complete. You should not rely upon it and should seek qualified advice before making any investment decision. Except where liability under any statute cannot be excluded, we do not accept any liability (whether under contract, tort or otherwise) for any resulting loss or damage of the reader or any other person.  Past performance is not a reliable guide to future returns.
Important: Any information provided by the author detailed above is separate and external to our business and our Licensee. Neither our business nor our Licensee takes any responsibility for any action or any service provided by the author. Any links have been provided with permission for information purposes only and will take you to external websites, which are not connected to our company in any way. Note: Our company does not endorse and is not responsible for the accuracy of the contents/information contained within the linked site(s) accessible from this page.

Disclaimer This service is provided solely for general information purposes. By providing this service ASIC does not provide legal or other professional advice. ASIC expressly disclaims any liability arising from use of the unclaimed money service. If you require legal or other expert advice or assistance, you should seek the services of an appropriately qualified professional.

Read our Privacy Policy ASIC uses the information you provide in the search to check for possible matches on the register. By accessing the register you agree to our handling of your personal information as set out in the ASIC Privacy Policy.

Terms and Conditions By using the search function to look for unclaimed money, you acknowledge you have read and agree to be bound by these terms and conditions. By accessing the unclaimed money search, you agree you will: Only use the information on the register for the purpose of searching and claiming an amount listed on the register; and Comply with any privacy legislation governing the use and disclosure of information from the register.


Companies are increasingly reaching substantial scale before entering public markets. This has renewed interest in how unusually large initial public offerings, or mega IPOs, enter stock market indexes and what their inclusion could mean for index fund investors.


Although a newly public company may have a significant headline valuation, its initial effect on a diversified index fund may be modest. That is because index inclusion follows each benchmark provider’s methodology, and a company’s weight generally reflects the value of shares that public investors can buy and sell rather than its total valuation.

Why are mega IPOs attracting attention now?

Companies are generally staying private longer, supported by greater access to private capital. By the time they pursue a public listing, some may be larger and more mature than the typical IPO of the past.

There is no single, industrywide definition of a mega IPO. The term generally describes a newly listed company whose market value would place it among the largest publicly traded businesses. Individual index providers apply their own size thresholds, often by comparing the company with existing index constituents or market capitalisation breakpoints.

The emergence of these companies presents index providers with two important objectives:

  • Representativeness: Reflecting economically significant companies once they become part of the public market.

  • Investability: Ensuring that the shares included in an index can reasonably be purchased and traded by investors.

Waiting several months to add a very large public company could leave an index temporarily less representative of its market. Adding it too quickly, however, could raise concerns about available liquidity, price formation, and the accuracy of ownership data. Index methodologies seek to balance these considerations through transparent eligibility and implementation rules.

When do IPOs enter stock market indexes?

There is no universal timetable. An IPO must satisfy the rules of the specific benchmark, which may address company size, liquidity, public float, domicile, security type, listing venue, and trading history.

Under a traditional inclusion process, an IPO may wait until a scheduled quarterly, semiannual, or annual index review. Some methodologies also require a minimum period of public trading, often called a seasoning period.

Fast-entry rules allow certain large IPOs to enter sooner. Depending on the benchmark, a qualifying IPO may be included approximately five to 15 trading days after listing. Approaches vary across index providers and even among indexes maintained by the same provider. For example, certain broad-market indexes permit fast entry, while the S&P 500 continues to require a longer trading history and satisfaction of its other eligibility criteria. 

A mega IPO does not receive automatic index inclusion because of its size, visibility, or expected performance. It must still meet the benchmark’s applicable eligibility requirements.

How large a weight will a mega IPO have in an index fund?

The answer generally depends more on the company’s float-adjusted market capitalisation than on its total valuation.

Free float refers to shares available for public investors to buy and sell. Shares held by founders, employees, controlling owners, governments, or other strategic investors may be excluded or discounted when an index provider calculates a company’s investable weight.

Essentially, float-adjusted market capitalisation equals the share price multiplied by the total number of publicly available shares.

Consider a hypothetical company with a total market value of $500 billion. If only 5% of its shares are considered publicly available, its initial float-adjusted market capitalisation will be approximately $25 billion. Its index weight will generally be based on that investable value, not the full $500 billion valuation. 

Investable size and index methodology matter more than headline valuation, with exposure generally building as public ownership expands. 

Note: The example is illustrative only and is based on the factors stated. It should not be taken to contain or provide an estimate or forecast of the size, valuation or index weighting of any company.

Why can the weight change over time?

The number of shares available to public investors often increases after an IPO. 

Lock-up agreements may temporarily prevent founders, employees, and early investors from selling shares. As restrictions expire, or as a company completes follow-on offerings and secondary sales, additional shares may become publicly available. This can increase the company’s float-adjusted market capitalisation and its index weight.

Index providers may reflect these changes during scheduled reviews or after qualifying corporate events. Significant float increases may also be incorporated gradually to support orderly trading and benchmark replicability.

As a result, the expiration of lock-ups and subsequent float adjustments may have a greater portfolio effect than the IPO’s initial index inclusion.

How do portfolio managers incorporate mega IPOs?

Inclusion is rules-based, but adding a large IPO to an index portfolio involves more than purchasing shares at the close of trading on the inclusion date. Portfolio managers must balance benchmark alignment with liquidity, transaction costs, market impact, taxes, and the potential for later float changes.

Portfolio managers may obtain exposure through a combination of IPO allocations, secondary-market purchases, fund cash flows, and carefully timed trading. The specific approach depends on the benchmark, available liquidity, relative pricing, and the fund’s investment objective.

The index provider determines whether and when a company enters the benchmark. The portfolio manager’s role is to implement that change efficiently. Vanguard’s scale, experienced investment teams, and disciplined trading processes support the incorporation of index changes while seeking tight tracking and low implementation costs.  

What should index fund investors remember?

Mega IPOs can generate significant attention, but their effect on a diversified index fund may be more measured than headline valuations suggest.

Three principles can help investors put mega IPOs and their index inclusion in perspective:

  1. Index inclusion is rules-based. A company enters an index when it satisfies the benchmark’s methodology, not because of investor enthusiasm or expected performance.

  2. Investable size matters. A company with a large total valuation but limited public float may initially receive a modest index weight.

  3. Diversification limits dependence on a single company. A broad index fund provides exposure to the development of public markets without requiring investors to predict which individual IPOs will succeed.

For long-term investors, the central principle remains unchanged: Broad, rules-based indexes seek to represent the market that investors can access. As public ownership of a newly listed company expands, its index representation can expand with it.

Notes: 
This article contains factual information only that is of a general nature. It does not contain financial product advice. We have not taken your objectives, financial situation or needs into account when preparing the information so it may not be applicable to your circumstances. 

All investing is subject to risk, including the possible loss of principal. Diversification does not ensure a profit or protect against a loss. An index fund is subject to the risks of the market or markets it tracks, and its value may rise or fall.

Source: Vanguard
Reproduced with permission of Vanguard Investments Australia Ltd
Vanguard Investments Australia Ltd (ABN 72 072 881 086 / AFS Licence 227263) is the product issuer. We have not taken yours and your clients’ circumstances into account when preparing this material so it may not be applicable to the particular situation you are considering. You should consider your circumstances and our Product Disclosure Statement (PDS) or Prospectus before making any investment decision. You can access our PDS or Prospectus online or by calling us. This material was prepared in good faith and we accept no liability for any errors or omissions. Past performance is not an indication of future performance.
© 2026 Vanguard Investments Australia Ltd. All rights reserved.
Important: Any information provided by the author detailed above is separate and external to our business and our Licensee. Neither our business nor our Licensee takes any responsibility for any action or any service provided by the author. Any links have been provided with permission for information purposes only and will take you to external websites, which are not connected to our company in any way. Note: Our company does not endorse and is not responsible for the accuracy of the contents/information contained within the linked site(s) accessible from this page.


What might seem like a quick financial benefit can lead to significant long-term costs and consequences for workers, businesses and company directors.

Workers paid cash-in-hand or ‘off the books’ miss out on superannuation, workplace protections and other employment entitlements, like annual leave, long service leave and public holidays. They can be overwhelmed with additional tax liabilities, penalties and interest if income isn’t declared and later identified. Workers may also discover they can’t verify their income when applying for loans, mortgages, or rental properties, or that their superannuation hasn’t been paid when they go to retire.

Paying workers correctly is one of the most important responsibilities of running a business. Employers that deliberately avoid their obligations may face audits, substantial tax liabilities, penalties up to 100%, interest charges and, in serious cases, prosecution. But the consequences can also be personal. Company directors are personally liable for PAYG withholding and super debts. In some cases, they may be prevented from leaving Australia until their debts are paid or funds can be recovered from their personal bank accounts through ATO garnishee action.

The following case study highlights what can happen when employers do the wrong thing.

Case study: Perth restaurant group hit with 2.8 million bill for hidden cash sales

Rita and Dan operate a chain of fast-food restaurants across Perth. Although each business had its own ABN, they shared directors, employees, and financial arrangements.

The ATO audited the group and found they had failed to:

  • report significant cash sales

  • pay staff through payroll systems, instead paying them in cash

  • withhold and remit PAYG withholding amounts

  • pay workers super guarantee entitlements

  • maintain adequate employee payroll records.

As a result, the businesses were issued with liabilities of more than $2.8 million for income tax, GST and super guarantee obligations as well as over $1 million in penalties and interest. The penalties and interest related to making false or misleading statements and failing to meet their obligations

Despite providing the directors multiple opportunities to address the group’s growing tax debts, they failed to take appropriate action. Instead, the ATO commenced recovery action, including issuing garnishee notices on bank accounts and merchant facilities to recover the outstanding amounts. These actions reinforced the serious consequences of failing to meet tax and super obligations.

The ATO takes this type of shadow economy activity seriously. These actions are illegal and create an unfair advantage over honest employers who are meeting their obligations. It also reduces funding available for essential services the Australian community rely on, while significantly impacting individual workers’ retirement savings and their financial security.

How to get it right

To help meet your employer obligations:

  • report all income, including cash payments

  • withhold, report, and pay PAYG withholding correctly and on time

  • pay super guarantee contributions for all eligible workers in full, on time and to the right fund

  • maintain accurate records of all business transactions, including employee details, hours, wages and super payments

  • seek advice from the ATO or speak to us early if you’re having difficulty meeting your obligations.

Meeting your obligations helps protect employees, supports business sustainability and contributes to a fair and trusted tax system.

Source: ATO
Reproduced with the permission of the Australian Tax Office. This article was originally published on https://www.ato.gov.au/businesses-and-organisations/small-business-newsroom/the-real-cost-of-cash-in-hand-arrangements. Important: This provides general information and hasn’t taken your circumstances into account. It’s important to consider your particular circumstances before deciding what’s right for you. Although the information is from sources considered reliable, we do not guarantee that it is accurate or complete. You should not rely upon it and should seek qualified advice before making any investment decision. Except where liability under any statute cannot be excluded, we do not accept any liability (whether under contract, tort or otherwise) for any resulting loss or damage of the reader or any other person. Any information provided by the author detailed above is separate and external to our business and our Licensee. Neither our business nor our Licensee takes any responsibility for any action or any service provided by the author. Any links have been provided with permission for information purposes only and will take you to external websites, which are not connected to our company in any way. Note: Our company does not endorse and is not responsible for the accuracy of the contents/information contained within the linked site(s) accessible from this page.

When you take out a home loan, one of the biggest decisions is whether to choose a fixed or variable interest rate. 

Choosing a home loan 

Buying a home is a big financial commitment, and choosing the best home loan for you is important. 

Even small differences in interest rates, fees and loan features can add up to thousands of dollars over the life of a loan. One of the biggest decisions you’ll make is whether to choose a fixed or variable interest rate. 

Each option has benefits and drawbacks. The right choice depends on your budget, circumstances and how much certainty or flexibility you need. 

What is a fixed rate home loan? 

A fixed interest rate stays the same for a set period, usually between one and five years. During that time, your repayments won’t change, even if market interest rates rise or fall. 

When the fixed period ends, your loan will usually move to the lender’s variable interest rate (revert rate) unless you switch home loans or agree to another fixed-rate period. 

Benefits of a fixed rate home loan 

  • you’ll know exactly what your repayments will be

  • budgeting can be easier

  • you’re protected if interest rates rise during the fixed period. 

Things to consider 

  • you won’t benefit if interest rates fall

  • you may be charged a break fee if you switch home loans, sell the property or pay off the loan early 

  • some fixed-rate loans have fewer features (like offset accounts or the ability to make extra repayments) than variable loan. 

Questions to ask before choosing a fixed-rate home loan 

  • What variable interest rate (revert rate) is likely to apply when the fixed period ends? 

  • How much could my repayments increase? 

  • Can I switch to another loan when the fixed period ends? 

  • What fees or charges could apply if I refinance before the end of the fixed-rate period? 

Understanding what happens after the fixed period can help you avoid unexpected increases in your repayments. 

What is a variable rate home loan? 

A variable interest rate can go up or down over time. Your lender decides whether to change the rate and by how much. 

Changes to the RBA cash rate may influence variable home loan rates, but lenders can also change rates for other reasons. If your interest rate rises, your repayments may increase. If it falls, your repayments may decrease. 

Benefits of a variable rate 

  • your repayments may decrease if interest rates fall

  • it is often easier to refinance or switch loans 

  • many variable loans allow extra repayments 

  • features such as offset accounts and redraw facilities are often available. 

Things to consider 

  • your repayments can increase unexpectedly when interest rates change

  • budgeting can be more difficult because costs may change. 

Questions to ask before choosing a variable-rate home loan 

  • How much could my repayments increase if interest rates rise? 

  • When and how will the lender tell me that my interest rate or repayments are changing? 

  • Does the loan allow extra repayments without fees? 

  • Are features such as an offset account or redraw facility available? 

  • What fees or charges could apply if I refinance or switch loans? 

In particular, if you’re borrowing close to your limit, think carefully about how you would manage higher repayments if interest rates rise. 

Important:
Your circumstances may change over the life of your loan. Before choosing a fixed or variable rate, consider whether you’ll want to make extra repayments, refinance or pay off the loan early, and check what fees or restrictions may apply. 

Compare fixed and variable home loan rates

Fixed rate

Variable rate

Repayments stay the same during the fixed period 

Repayments can rise or fall 

Can make budgeting easier 

Can make budgeting less predictable 

Protects you from rate rises during the fixed period 

You may benefit if rates fall

May limit extra repayments

Often allows extra repayments 

Break fees may apply if you switch or refinance

It is often easier to switch loans

May have fewer loan features 

Offset and redraw features are often available 

Usually moves to a variable rate when the fixed period ends 

Continues as a variable rate unless you switch or change the loan 

 A split home loan gives you some of both 

 A split home loan divides your loan into two parts. One part has a fixed rate and the other has a variable rate. You can agree with the lender how much of the loan to allocate to each part. 

 A split loan can give you: 

  • more certainty over repayments on the fixed part 

  • flexibility to make extra repayments on the variable part 

  • access to features that may be available on the variable part. 

A split loan can also be more complex. Different rates, fees, features and conditions may apply to each part, so check the total cost before you choose. 

Questions to ask about a split loan 

  • How much of the loan will be fixed and how much will be variable? 

  • What fees apply to each part? 

  • Can I make extra repayments on either part? 

  • Which part can be linked to an offset account? 

  • What happens to the fixed part when the fixed period ends? 

Work out what you can afford to borrow 

No matter what type of home loan you choose, be realistic about what you can afford. 

Use a mortgage calculator or contact us to see how a higher interest rate could affect your repayments and the total cost of your loan. 

Try more than one interest rate so you can see whether your budget has room for repayments to rise – ideally calculate what your costs would be if interest rates went up by 3%.  

Look beyond just the home loan interest rate 

The home loan interest rate is not the only cost to compare. It’s important to also compare fees, loan features and repayment amounts. Also think about how much certainty or flexibility you may need in future. 

We can help you to understand and what to compare when looking for a home loan.

If you are considering an offset account or redraw facility, we can tell you how they work and check the fees, conditions and access rules. 

Contact us if you have any questions about home loans and how they work.
Source: Moneysmart
Reproduced with the permission of ASIC’s MoneySmart Team. This article was originally published at https://moneysmart.gov.au/home-loans/fixed-vs-variable-home-loan-interest-rates
Important note: This provides general information and hasn’t taken your circumstances into account.  It’s important to consider your particular circumstances before deciding what’s right for you. Although the information is from sources considered reliable, we do not guarantee that it is accurate or complete. You should not rely upon it and should seek qualified advice before making any investment decision. Except where liability under any statute cannot be excluded, we do not accept any liability (whether under contract, tort or otherwise) for any resulting loss or damage of the reader or any other person.  Past performance is not a reliable guide to future returns.
Important: Any information provided by the author detailed above is separate and external to our business and our Licensee. Neither our business nor our Licensee takes any responsibility for any action or any service provided by the author. Any links have been provided with permission for information purposes only and will take you to external websites, which are not connected to our company in any way. Note: Our company does not endorse and is not responsible for the accuracy of the contents/information contained within the linked site(s) accessible from this page.

Key Points

  • Democrat wins in the US midterms signal: Trumpism has peaked; Congress will now be a check on him; more regulation on AI; a return to debt ceiling brinkmanship; the risk Trump refocuses on foreign policy including the War and tariffs; and fears of tax hikes and bigger government.

  • The blue wave is probably negative for bonds, ambiguous for shares with correction risk remaining but the 6-12-mth outlook looking okay and a small negative for crypto.

  • For Australia, a risk is a renewed Trump focus on disruptive foreign policy in the near term (tariffs and/or War) but this should recede as Trump’s power wanes.  

  • Lower oil prices reduce the chance of another rate hike, but our view remains for RBA to be on hold out to late next year.

Introduction

The US midterms saw a resounding rebuke of President Trump’s policies, with Democrats taking control of the House and the Senate, with big wins and various governorships in Republican states. Naturally Trump has tried to deflect – arguing if “I was on [the ballot] we would have won in a landslide”. Ironically, he’s ignoring the fact that he had asked people to assume he was on the ballot. Maybe they did! But, as always “it’s the economy, stupid”. Trump won in 2024 because “cost of living” pressures turned people against the Democrats, but his crazy tariff and War policies made them even worse causing those who swung to him then to swing back to the Democrats. This wasn’t helped by the ICE raids, the Epstein files, attacks on democracy, perceptions of graft & corruption & Trump’s crazy focus on things like his ballroom, triumphal arch and gold trinkets in the Oval Office.

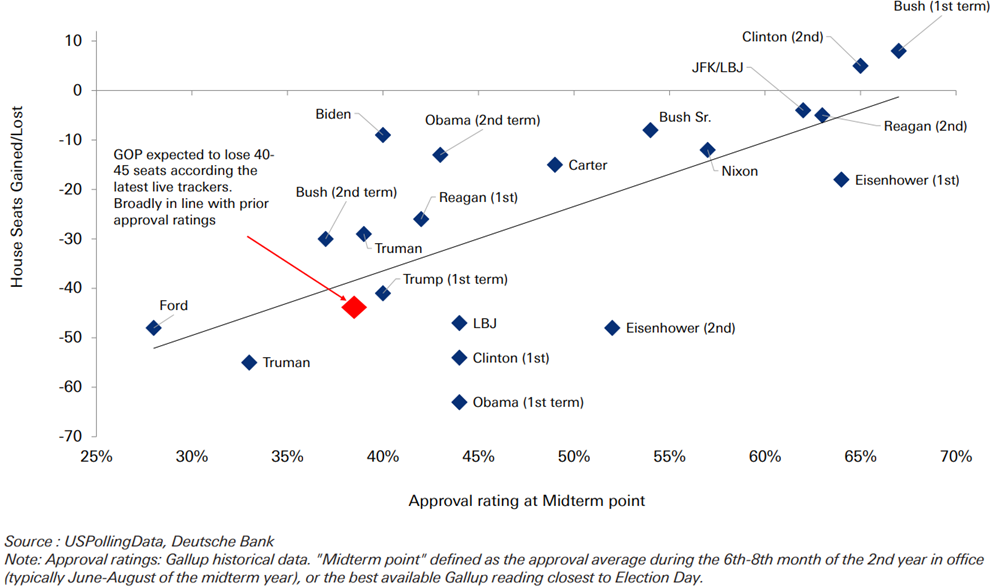
There is a danger in reading too much into it as presidents often lose Congress in midterms. Clinton & Obama lost more seats in their first term midterms & went on to win second terms (not that Trump can run again).

Presidential approval rate versus House seats lost in Midterms

Source : Deutsche Bank

Implications for US economic policy

However, the blue wave does have significant implications particularly given Trump’s sensitive character. In particular:

  • Trumpism has probably peaked, having been rejected even in several red states. People like Majorie Taylor Green just recognised the problem early. That said Trump is still President for two more years so there is still plenty of opportunities for him to create mayhem.

  • However, Congress will now be a check on Trump and in particular there are now likely to be significant inquiries into his and the Administration’s actions including a possible attempt at impeachment of Trump or at least his team. Democrat control of the Senate also means Fed independence will be protected. At a high level this once again highlights that US governance and democracy remains strong – a slide into strong man dictatorship is not going to happen as US voters won’t permit it. Some surveys showed democracy as just as important an issue for voters as the economy.

  • More regulation of AI – particularly on data centres in states where Democrats won the governorship (Texas, Ohio, Iowa and Georgia). There is danger in exaggerating this though. Trump can veto regulations from Congress, but the states may matter more. That said there are still plenty of states that may welcome data centres.

  • A return to brinkmanship over raising the debt ceiling (necessary by around June quarter next year and funding the US Government (which currently expires on 11th December) – in some ways this may be a good thing if it leads to a smaller budget deficit. However, hopes for lower budget deficits may prove in vain as Trump may agree with Democrats to increase some social benefits if they support more defence spending, and he is likely to veto tax hikes

  • Trump moving into being a lame (or angrier) duck President could see him become more aggressive in foreign policy by, eg, ramping up the war on Iran and returning to the tariff war. So far markets seem relaxed, with oil prices down on hopes Congress will bring an end to the War, VP Vance & other Republicans blaming the War for the election loss and reports that the US and Iran may be edging closer to a deal again. And both tariffs and the War are self-evidently not popular so Republicans may cut him adrift if he pushes heavily down this path again. That said he could still have a go just to prove who’s in charge – so another spike in tariffs and/or oil prices remains a high risk. His replacement of Susie Wiles with hardliner Stephen Miller suggests Trump may not be about to moderate his policies.

  • Fears that tax hikes and bigger government are on the way particularly if a Democrat wins the 2028 presidential election. However, the risks on this front are overstated. Sure, the numbers of DSA (Democrat Socialists) in Congress will increase but most of the wins owed to moderate centre left Democrats particularly in must win (for 2028) red states, suggesting the US has not lurched to Bernie Sanders/AOC style democratic socialism. The failure of the 5% billionaire wealth tax proposal in California also supports this view although not strongly as one reason for opposing it was that it wasn’t national (so risked a loss of billionaires out of California).

Implications for major asset classes

Oil – ambiguous near term/negative over the medium term
Sure, oil prices have fallen since the midterms on hopes Trump has got the message that the War is unpopular, hopes a Democrat Congress will end it and hopes talks will lead to a deal. But the talks have been going in circles since April, & he may ramp the War up again to show whose boss – driving one last spike in oil prices. However, on a medium term view the US is likely to wind down the War under pressure from Congress and many Republicans who are likely to be far less supportive of Trump now.

Bonds – negative
Again, bond yields have fallen since the midterms on the fall in oil prices and hope political gridlock will lead to a lower budget deficit. However, there is a high risk Trump will have one last go in the Iran War which could push oil prices up. And Trump may agree with Democrats to increase some social benefits if they support more defence spending and he is likely to veto tax hikes – which could worsen the deficit.

Shares – ambiguous
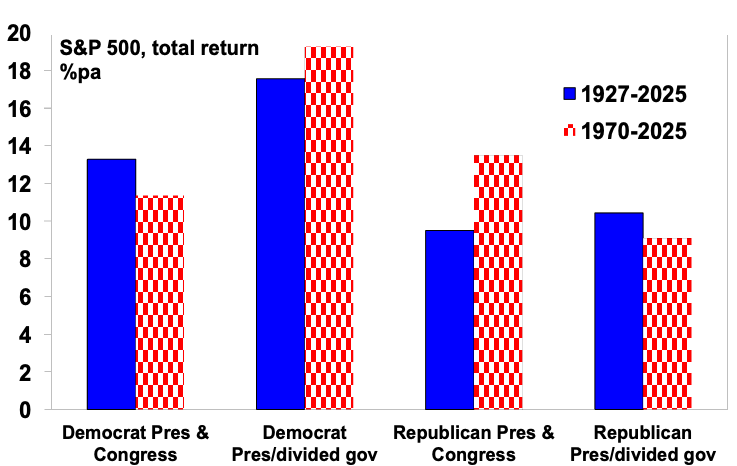
The bad news is that the combination of a Republican president and Democrat control of one or both houses of Congress has been the worst outcome for US share returns on average since 1970, with an average return of 9.1%pa compared to 13.5%pa when there is a Republican president and congress. Of course, 9.1% is still okay!

US Share market returns by political configuration

Source : Bloomberg, AMP

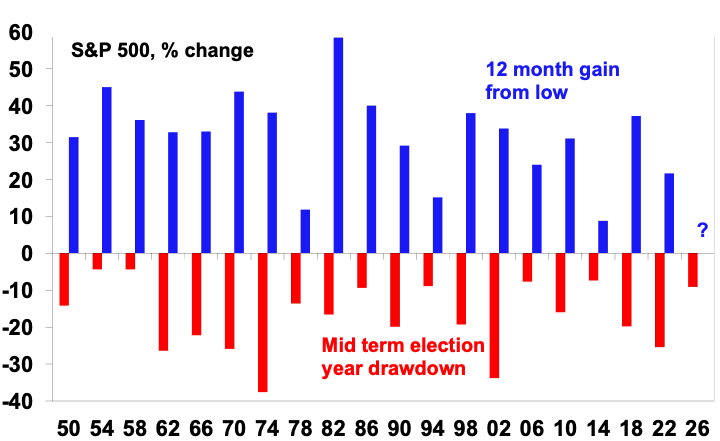
The good news is that US shares have risen following all midterm elections since 1950 given the removal of a source of uncertainty. 

US Shares around midterms elections

Source: Bloomberg, AMP

However, there may be more uncertainty this time around given the risk for the AI trade and its high weight in the US share market and recent US economic growth along with Trump’s unpredictability and the risk he could go rogue for a while now that the election is out of the way.

So far, the US share market has had a roller coaster reaction to the midterms – up 1.6% initially on the back of lower oil prices then down 4.4% on Thursday. And share investors are a bit schizophrenic around data centres – yes, they sold off heavily on Thursday on fears that Democrat wins will constrain them but earlier they had been selling off on fears that hyperscaler AI capex was excessive and uneconomic. So, if it’s the latter then constraints on data centre buildouts may do investors a favour! In any case while more regulations may be put around data centres its unlikely to fundamentally stop their build out. Since Thursday there has been a recovery in US shares leaving them around where they were before the midterms!

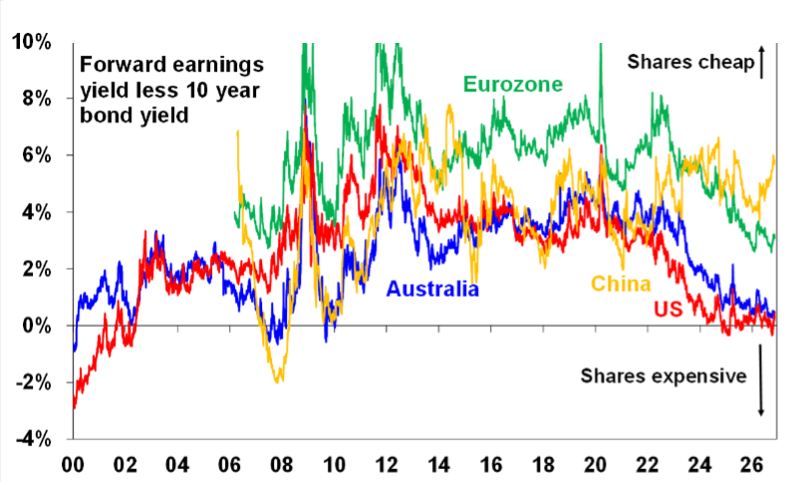
Overall, the risk of a further correction in shares remains high given the threats from high and sticky inflation, ongoing central bank rate hikes, excessive public debt driving rising bond yields, the risk of one last spike in oil prices, AI bubble and data centre worries, and slowing growth and rising rates in Australia. And despite some fall in price to earnings ratios and more recently a pullback in bond yields both US and Australian shares remain expensive relative to bonds as measured by the gap between forward earnings yields and bond yields which is a proxy for the risk premium shares offer over bonds. Of course, the risk premium has been low for years now so it’s not a great timing guide for shares.

Equity risk premium over bonds

Source: Bloomberg, AMP

However, at this stage strong US earnings growth (even outside tech) and no indications of a US recession suggest that any pull back in shares is more likely to be a correction rather than a new bear market. So, we continue to see shares providing okay returns on a 6-12 month horizon.

Cryptocurrencies – negative
With Democrats likely to look closely at the Trump family’s links to the sector the tide may be turning back towards tougher crypto regulation. Bitcoin will likely retain support though as an inflation hedge.

Gold and the $A – ambiguous
Much here will depend on oil and how much further the Fed has to hike but the midterms are unlikely to have a decisive impact here.

Implications for Australia

While the fall in oil prices may mean less pressure on the RBA for another hike, it’s uncertain as to whether this will stick in the short term and we see no reason to alter our assessment that the RBA will leave rates on hold out to late next year.

At a broader level, a risk for Australia is a renewed Trump focus on disruptive foreign policy in the near term (tariffs and/or the Iran War) but this should recede as Trump’s power wanes over the next two years. 

Dr Shane Oliver – Head of Investment Strategy and Chief Economist, AMP
Important note: While every care has been taken in the preparation of this document, AMP Capital Investors Limited (ABN 59 001 777 591, AFSL 232497) and AMP Capital Funds Management Limited (ABN 15 159 557 721, AFSL 426455) make no representations or warranties as to the accuracy or completeness of any statement in it including, without limitation, any forecasts. Past performance is not a reliable indicator of future performance. This document has been prepared for the purpose of providing general information, without taking account of any particular investor’s objectives, financial situation or needs. An investor should, before making any investment decisions, consider the appropriateness of the information in this document, and seek professional advice, having regard to the investor’s objectives, financial situation and needs. This document is solely for the use of the party to whom it is provided.

Retirement confidence isn’t just about your nest egg, it’s about your plan

Do you know how much interest you pay on your mortgage?

Chances are you do. Like many homeowners, you may follow the Reserve Bank’s interest rate decision closely. You know what your repayments are, how much rates have risen over recent years and what that means for your household budget.

Now consider another question.

Do you know the fees you pay on your superannuation account?

For many Australians, superannuation is their second largest asset after the family home. Yet recent retirement research found that one in two of us would not feel confident explaining the fees charged on their super account.1 At the same time, almost two-thirds could not correctly identify the age at which you can access super.2

The contrast is revealing.

The issue isn’t that Australians don’t care about retirement. It’s that retirement often remains a future problem until suddenly it becomes a present one.

Why confidence isn’t just about money

When Australians think about retirement, the conversation usually starts with money.

How much super do I need? Will I be able to retire comfortably? Am I on track?

They’re important questions. Yet one of the clearest findings from our research is that retirement confidence isn’t just about how much you’ve saved. It’s also about whether you’ve started planning for the future you want.

Australians with a retirement plan are significantly more likely to feel confident about retirement than those without one. Nearly half of working-age Australians, however, have no retirement plan at all.3

Too many Australians see retirement as a distant milestone rather than a life stage worth planning for today. As a result, retirement preparation is often delayed until people feel they have enough time, enough money or enough knowledge to tackle it properly. For many, that moment never quite arrives. 

The research also suggests many Australians are navigating retirement largely on their own. Around one in three rely primarily on their own research when making retirement plans, while partners, family and friends are consulted more often than financial advisers.4 This highlights how important it is that Australians have access to clear, practical information that helps them make informed decisions about their future.

A different retirement awaits younger Australians

In today’s economic landscape, it’s never been more important for young Australians to plan for the future.

While many of today’s retirees own their homes outright, our research shows younger Australians increasingly expect to enter retirement with mortgage debt or while renting. Combined with longer life expectancies, rising housing costs may make it more expensive to maintain the retirement lifestyle they hope to enjoy.

Yet planning for retirement doesn’t need to start with spreadsheets or complex calculations. It can begin with a much simpler question: what kind of life do you want to live?

This research found Australians overwhelmingly view retirement as an opportunity to maintain their independence, enjoy good health, spend time with family and friends, and pursue leisure activities. In fact, these lifestyle aspirations consistently rank alongside financial security as key ingredients of a successful retirement.

So, where do you want to live? Will you continue working? What role will travel, health and family play in your future?

These are lifestyle questions before they’re financial ones. Yet they often provide the starting point for a meaningful retirement plan. Once people have a clearer picture of the retirement they want, they are better positioned to make the financial decisions that support those goals.

Make a start

Retirement planning is not a single decision made at the end of a career. It is a series of decisions made over many years, often starting with one small step.

Take small, practical steps towards your financial future.

Getting started can be as simple as checking your super account, understanding the fees you pay, or having a conversation with your partner about your future. Small actions can build understanding, confidence and ultimately help Australians feel better prepared for retirement.

To start your retirement journey, talk to us.

Footnotes:
1. How Australia Retires 2026, 14
2. How Australia Retires 2026, 12
3. How Australia Retires 2026, 22
4. How Australia Retires 2026, 24

Source: Vanguard

This article has been reprinted with the permission of Vanguard Investments Australia Ltd. Copyright Smart Investing™
Reproduced with permission of Vanguard Investments Australia Ltd Vanguard Investments Australia Ltd (ABN 72 072 881 086 / AFS Licence 227263) is the product issuer. We have not taken yours and your clients’ circumstances into account when preparing this material so it may not be applicable to the particular situation you are considering. You should consider your circumstances and our Product Disclosure Statement (PDS) or Prospectus before making any investment decision. You can access our PDS or Prospectus online or by calling us. This material was prepared in good faith and we accept no liability for any errors or omissions. Past performance is not an indication of future performance. © 2026 Vanguard Investments Australia Ltd. All rights reserved. Important: Any information provided by the author detailed above is separate and external to our business and our Licensee. Neither our business nor our Licensee takes any responsibility for any action or any service provided by the author. Any links have been provided with permission for information purposes only and will take you to external websites, which are not connected to our company in any way. Note: Our company does not endorse and is not responsible for the accuracy of the contents/information contained within the linked site(s) accessible from this page.

The Higher Everyday Living Fee, or HELF, is a new optional fee that lets aged care residents pay for a more premium experience, from better meals to in-room entertainment. It’s completely optional, and declining it shouldn’t affect the standard care you receive. This guide breaks down what HELF actually covers, how it’s priced, and the exact questions to ask your provider before you sign anything.

When comparing aged care homes, you might have come across the term Higher Everyday Living Fee (HELF). This is HELF, introduced in November 2025, and made to give aged care home residents the option of a more premium experience. But what is it, how much is it, and how does it affect you or your loved one?

What is HELF?

In simple terms, HELF is a fee for extra services in residential aged care homes. This includes “higher living” services like premium meals, in-room television services, Wi-Fi usage, just to name a few. It’s taken over the need for multiple fees at once, like the Extra Service Fee and Additional Service Fee.

Is HELF compulsory?

The good news is that it’s a completely optional fee, and you can choose whether you or your loved one is willing to pay for the premium service. If you don’t choose to pay for this option, you shouldn’t be forced or charged for it by a provider. 

What if I don’t want to pay for HELF? Will I get less than others?

As per the law, non-HELF-paying residents will not be given lesser living conditions. All residential aged care residents will receive standard high-quality care and services under the Aged Care Quality Standards and the Service List, but HELF-paying residents will simply receive additional benefits. 

Choosing not to pay for HELF won’t prevent you from finding a place in a home, but a specific room you’re interested in may come with the fee built in. When looking at a particular facility, ask for the fee, and your right to decline it, in writing. Providers should be transparent and clear about how HELF comes into play in their particular facility. 

How much is HELF?

HELF is also not a “one size fits all” service fee. Each establishment and its provider sets its own price and services, all at its own discretion. Prices vary between different aged care homes and sometimes between rooms in the same facility. It’s important to ensure that you know exactly how much the home will be charging you for your specific choices. 

Before agreeing to anything in writing, make sure you’re clear on what you’re signing 

Here are some questions to ask your provider to get a better picture of how it will affect you: 

  • How much is HELF for this particular provider?

  • What are the premium services that come with this fee for this particular provider?

  • Do I still have to pay it even if I don’t use all the services?

  • How often is HELF charged?

  • How much notice will I get if the price goes up?

HELF is one part of a much bigger picture. When selecting a residential facility, you will encounter basic daily fees, means-tested care contributions, and accommodation costs, with this new premium option potentially added to the mix. None of it needs to be worked out alone, and none of it needs to be decided on the spot.

Your checklist

  • Take the price list home. 

  • Ask for the details in writing. 

  • Compare a few homes before you choose. 

  • If a fee isn’t clear, ask again until it is.

Understanding a fee like HELF is just one step in finding the right home. With the right questions, and the right support, that step gets a lot easier to take.

Source: AgedCareGuide
Reproduced with permission of Care & Co Media. This article was originally published on https://www.agedcareguide.com.au/talking-aged-care/aged-care-101-what-is-higher-everyday-living-fee-helf Important: This provides general information and hasn’t taken your circumstances into account. It’s important to consider your particular circumstances before deciding what’s right for you. Although the information is from sources considered reliable, we do not guarantee that it is accurate or complete. You should not rely upon it and should seek qualified advice before making any investment decision. Except where liability under any statute cannot be excluded, we do not accept any liability (whether under contract, tort or otherwise) for any resulting loss or damage of the reader or any other person. Any information provided by the author detailed above is separate and external to our business. Our business does not take any responsibility for any action or any service provided by the author. Any links have been provided with permission for information purposes only and will take you to external websites, which are not connected to our company in any way. Note: Our company does not endorse and is not responsible for the accuracy of the contents/information contained within the linked site(s) accessible from this page.

It was pitched to investors as “the biggest initial public offering (IPO) in a generation”.

Firmus Technologies – a developer of artificial intelligence (AI) data centres – planned to raise A$7 billion from investors on the Australian Securities Exchange.

Recently, bankers working on the deal declared investor interest in the A$11-a-share offer was “well in excess” of what was needed to go ahead.

The company and its backers claimed Firmus was worth almost A$44 billion, which would have made it Australia’s second-largest share market listing, behind Telstra in 1997.

Then, it was off.

What went wrong? And what are the lessons investors should apply to all companies to guard against hype and protect their money?

The warning signs were obvious

There were plenty of red flags ahead of this listing, covered in detail by The Conversation, when the IPO was still meant to be going ahead.

Firmus is losing money. Only two of its data centres are currently operational, with the rest in the planning or construction phase.

Most remarkably, Firmus’ claimed value had soared almost eight-fold in less than a year.

In November 2025, a private funding round valued it at about A$6 billion. In August this year, it had climbed to more than US$10.5 billion (about A$15 billion).

Yet, Firmus declared its value was A$43.7 billion. At that price, Firmus would have been worth almost as much as retail giant Woolworths.

A sign of the market working

The role of the market is to digest a lot of information and price all of that into a reasonable value for each company. If investors believe a company is worth less than its IPO price estimate, they withdraw their interest.

In Firmus’ case, this declining interest from investors seems to be an example of the market working properly.

We never saw a public prospectus with all the details about this listing and Firmus’ financials; it was meant to be released, but it wasn’t.

However, a draft prospectus was being circulated to institutional investors here and overseas. They’ve looked at that – and the prospect of actually committing to buying those shares at A$11 a share – and many have decided “no thanks”.

That’s why the listing was withdrawn.

Look for the incentives behind any claim

As an economist, you always look out for incentives: why would someone say something? What might be in it for them?

There is a clear incentive for investment bankers to ramp up demand before any stock exchange listing. That’s because the higher the float price, the more they pocket, too.

So where did this demand go? It’s quite possible there was strong initial demand for Firmus shares, but it was only indicative. That usually comes down a bit before any listing – or down by a lot, as in Firmus’ case.

Some commentators have raised a more concerning possibility: that the level of investor demand in Firmus may have been misrepresented.

After the Firmus listing was cancelled, The Australian Financial Review reported:

While demand for IPOs can move around, serious questions need to be asked about the sheer scale of the evaporation of orders from investors, or whether the communications were misleading to create the perception of frenzied support. The onus is now on the Australian Securities and Investments Commission to come down hard on those flouting the rules.

We’ll have to see what emerges in coming weeks on this.

Is it a warning sign of an AI bubble?

Investors shouldn’t assume that Firmus’ issues are indicative of every other AI or data centre company.

A lot of this situation is specific to Firmus, including how quickly their quite outrageous valuation numbers ballooned in such a short time.

However, we did see similar things happening during the dot-com bubble a generation ago. Back then, a lot of companies were going public based on “thin air valuations” – projecting huge demand into the future, without the numbers to back it up.

That was echoed in what Firmus was doing now: operating with just 5% of data centre capacity up and running, while the remaining 95% they were talking about as underpinning their valuation hadn’t yet been built.

What are the lessons for investors?

Potential investors should look at the hard numbers as closely as they can.

If you can’t find out what a company’s revenue was in the past year, and where it expects its money will be coming from for the next five years, at least – that’s a red flag.

Of course, even if you have those figures, that doesn’t mean things won’t go wrong down the road. But understanding those key numbers is a must, before you ever invest.

The golden rules are to diversify your investment portfolio and try to minimise your fees. And if you are buying into a single company’s IPO, it’s safer to allocate limited amounts to those.

As a general rule: don’t invest in single stocks more than you can afford to lose.

Source: This article is republished from The Conversation

As an employer, it’s always been important to ensure your payroll data is accurate as it helps super funds match contributions to the right employee and process them without delay.

Under Payday Super, super contributions must generally be received by your employee’s super fund within 7 business days of payday. This makes data quality even more important to help you meet your super obligations.

Correct data helps contributions reach the right employee

To support successful super contributions, you should:

  • keep employee details up to date, including names, dates of birth, tax file number (TFN) and super account details

  • check employee information is accurate before processing payroll

  • work with your payroll or super service provider to resolve data issues promptly

  • review your payroll processes regularly to reduce errors.

Common data errors include:

  • invalid TFN

  • incorrect dates of birth

  • generic values added to employee records.

If the correct information isn’t available for an optional field, leave it blank rather than entering incorrect or substitute data. These data errors can delay the matching and allocation of contributions.

Member verification requests (MVR) reduce errors

An MVR allows you to verify that your employee’s super fund details are correct and that the fund can accept contributions. You can use an MVR:

Although many super funds and self-managed super funds are already responding to MVRs, not all funds are ready. You should check whether your payroll provider or clearing house is ready before sending an MVR. 

How to resolve data errors

If you receive an error message, you should:

  • review the error and follow any instructions from your provider

  • check the employee details are correct, including their name, date of birth, TFN and contact details

  • ask your employee to confirm the details they provided are correct

  • fix any inaccurate or incomplete information before you resubmit it.

You can resolve most issues by fixing this information, so you generally won’t need to contact the fund.

Unresolved data errors can cause the super fund to reject or return contributions. Maintaining accurate payroll data helps funds process and allocate contributions on time. This reduces delays and helps you meet your super obligations.

If you have any questions, give us a call.

Source: ATO
Important: This provides general information and hasn’t taken your circumstances into account. It’s important to consider your particular circumstances before deciding what’s right for you. Although the information is from sources considered reliable, we do not guarantee that it is accurate or complete. You should not rely upon it and should seek qualified advice before making any investment decision. Except where liability under any statute cannot be excluded, we do not accept any liability (whether under contract, tort or otherwise) for any resulting loss or damage of the reader or any other person. Any information provided by the author detailed above is separate and external to our business and our Licensee. Neither our business nor our Licensee takes any responsibility for any action or any service provided by the author. Any links have been provided with permission for information purposes only and will take you to external websites, which are not connected to our company in any way. Note: Our company does not endorse and is not responsible for the accuracy of the contents/information contained within the linked site(s) accessible from this page.